12 Personal Finance Tips That Actually Work in 2026
Good money habits are not about luck or a six-figure salary. They are built from small, repeatable decisions. The best personal finance tips focus on systems you can keep for years, not crash budgets you abandon by February. In this guide you will find twelve practical strategies, a comparison of popular budgeting methods, and answers to the questions readers ask most in 2026.
Inflation has cooled compared with the spikes of a few years ago, but the cost of housing, groceries, and insurance still pressures household budgets. That makes disciplined planning more valuable than ever. Let us walk through what works.
Why Personal Finance Tips Matter More in 2026
According to the U.S. Federal Reserve’s Economic Well-Being of U.S. Households report, a large share of adults still could not cover a sudden four-figure expense from savings. That single statistic explains why an emergency fund sits at the top of almost every expert’s list.
The goal is resilience. When your finances can absorb a surprise car repair or a gap between jobs, stress drops and better long-term decisions follow. The personal finance tips below are ordered to build that resilience step by step.
Build the Foundation First
1. Track every dollar for 30 days
You cannot fix what you cannot see. Spend one month recording income and expenses, either in a notebook or an app. Most people discover two or three leaks they never noticed, such as overlapping subscriptions.
2. Build a starter emergency fund
Aim for one month of essential expenses in a separate high-yield savings account, then grow it to three to six months over time. Keep it liquid and boring. This is insurance, not an investment.
3. Automate the boring parts
Set automatic transfers to savings on payday and autopay for fixed bills. Automation removes willpower from the equation, and willpower is the first thing to fail on a stressful week.
Smart Budgeting Methods Compared
No single budget suits everyone. The right method depends on how much detail you enjoy and how irregular your income is. The table below compares the three approaches most people try.
| Method | How it works | Best for | Effort |
|---|---|---|---|
| 50/30/20 | 50% needs, 30% wants, 20% savings and debt | Beginners who want simplicity | Low |
| Zero-based | Every dollar gets a job until income minus expenses equals zero | Detail-lovers and tight budgets | High |
| Pay-yourself-first | Save a set amount first, spend the rest freely | Steady earners who hate tracking | Medium |
Try one method for a full month before switching. Jumping between systems is one of the most common reasons budgets fail.
Cut Costs Without Feeling Deprived
Frugality fails when it feels like punishment. Instead, target the big three categories where small changes free up real money: housing, transportation, and food. Trimming a recurring cost once pays you every month for the rest of the year.
- Negotiate recurring bills. Call your internet and insurance providers annually and ask for current promotions.
- Audit subscriptions quarterly. Cancel anything you have not used in 60 days.
- Plan meals around sales. A loose weekly plan cuts both grocery spend and food waste.
- Buy quality once. For items you use daily, durable goods beat cheap replacements over time.
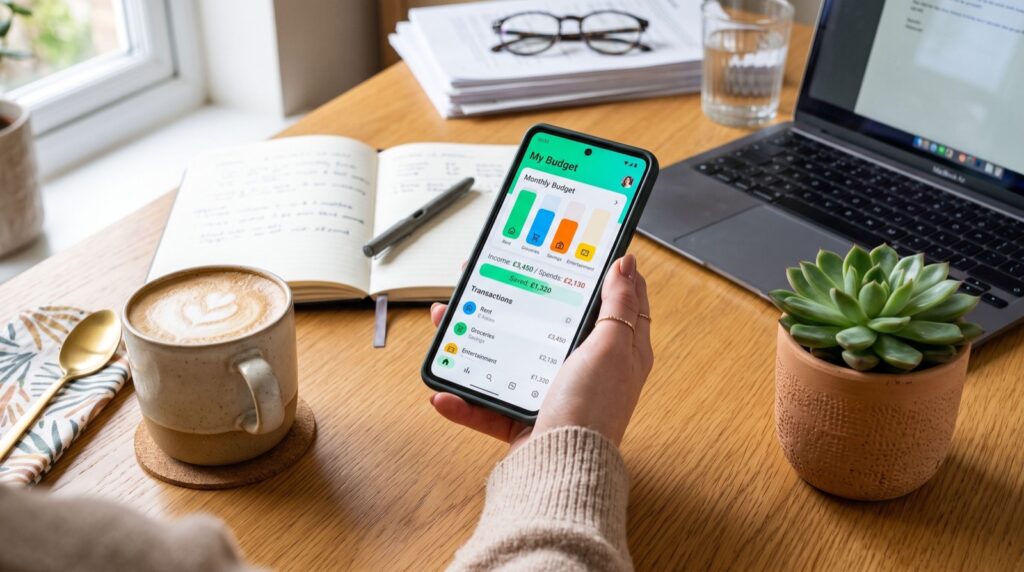
Pair these cuts with helpful tools. Many of the best money apps can flag unused subscriptions and round up spare change into savings automatically, turning good intentions into results.
Grow Wealth and Crush Debt
4. Attack high-interest debt first
Credit card APRs remain painfully high in 2026. Use the avalanche method, paying minimums on everything and throwing extra cash at the highest-rate balance first to save the most on interest.
5. Capture every employer match
If your workplace retirement plan offers a match, contribute at least enough to get it. That match is an instant, guaranteed return you will not find anywhere else.
6. Invest consistently, not perfectly
Low-cost, diversified index funds and steady monthly contributions beat trying to time the market. The U.S. Securities and Exchange Commission’s Investor.gov resource offers free, unbiased basics for new investors.
7. Review your credit report yearly
Errors are common and can cost you on loan rates. You are entitled to free reports, so check them and dispute mistakes promptly.
When to Get Outside Help
Doing it yourself works for most everyday decisions. But complex situations, like inheritance, small-business taxes, or retirement drawdown, deserve a professional. If your money picture feels tangled, consulting an experienced local team of fee-only advisors can prevent costly mistakes and give you a clear plan.
Choose advisors who are fiduciaries, meaning they are legally bound to act in your interest. Always ask how they are paid before you sign anything.
Set Goals You Can Actually Measure
Vague goals like “save more” rarely survive contact with real life. Specific, measurable targets do. Instead of promising to spend less, decide to move $200 to savings on the first of every month. A number you can check beats an intention you can only hope about.
Try attaching each goal to a timeline and a reason. A goal with a deadline and a purpose, such as “$6,000 for a car down payment by next December,” pulls you forward far harder than an open-ended wish.
8. Track net worth, not just spending
Your net worth, assets minus debts, is the single clearest scoreboard for financial progress. Update it once a month. Watching the number climb, even slowly, is one of the most motivating personal finance tips you can adopt.
9. Use short savings challenges
A time-boxed challenge makes saving feel like a game rather than a chore. Try a no-spend weekend or a 52-week savings plan where you bank a rising amount each week. Small wins build the confidence that fuels bigger ones.
10. Give every raise a job
When your income rises, send at least half of the increase straight to savings or debt before you adjust your lifestyle. Avoiding this lifestyle creep is how steady earners quietly build real wealth over a decade.
Protect What You Build
Earning and saving matter little if a single setback wipes it out. Adequate health, auto, and renters or homeowners insurance turns catastrophes into manageable inconveniences. Review your coverage once a year, especially after major life changes like marriage or a move.
Protect your identity too. Freeze your credit when you are not actively borrowing, use a password manager, and turn on two-factor authentication for every financial account. These habits cost nothing and prevent expensive headaches.
11. Keep a will and beneficiaries current
Even a simple estate plan spares your family confusion and expense. Name beneficiaries on your accounts and keep them updated after life events. It takes an afternoon and protects the people you care about most.
12. Review everything every quarter
Set a recurring 30-minute appointment with yourself every three months. Check your budget, savings rate, debt balances, and goals. Regular, low-pressure reviews catch small problems before they grow into big ones.
Frequently Asked Questions
What are the most important personal finance tips for beginners?
Start with three moves: track your spending for a month, build a small emergency fund, and automate your savings. These create the stability every other decision depends on.
How much should I keep in an emergency fund?
Begin with one month of essential expenses, then build toward three to six months. If your income is irregular, aim for the higher end of that range.
Which budgeting method is best?
The one you will actually stick with. Beginners often succeed with the simple 50/30/20 rule, while people on tight budgets benefit from zero-based budgeting.
Can money apps really improve my finances?
Yes, when used consistently. They reduce friction by automating transfers, tracking spending, and surfacing wasted subscriptions so you act on the data instead of guessing.
Conclusion
Lasting financial health comes from systems, not sprints. Pick two or three of these personal finance tips, put them on autopilot this week, and add another next month. Small, boring, repeatable steps compound into real security over time. Start today, stay consistent, and let your future self thank you.